ARGA places two funds in the Top 3, while Fidelity International makes its first Top 5 appearance.
Our latest Essentia Behavioral Alpha Benchmark ranking, covering the three years ended Sept. 30, 2026, assesses a record 205 active equity portfolios, up from 199 in the previous quarter.
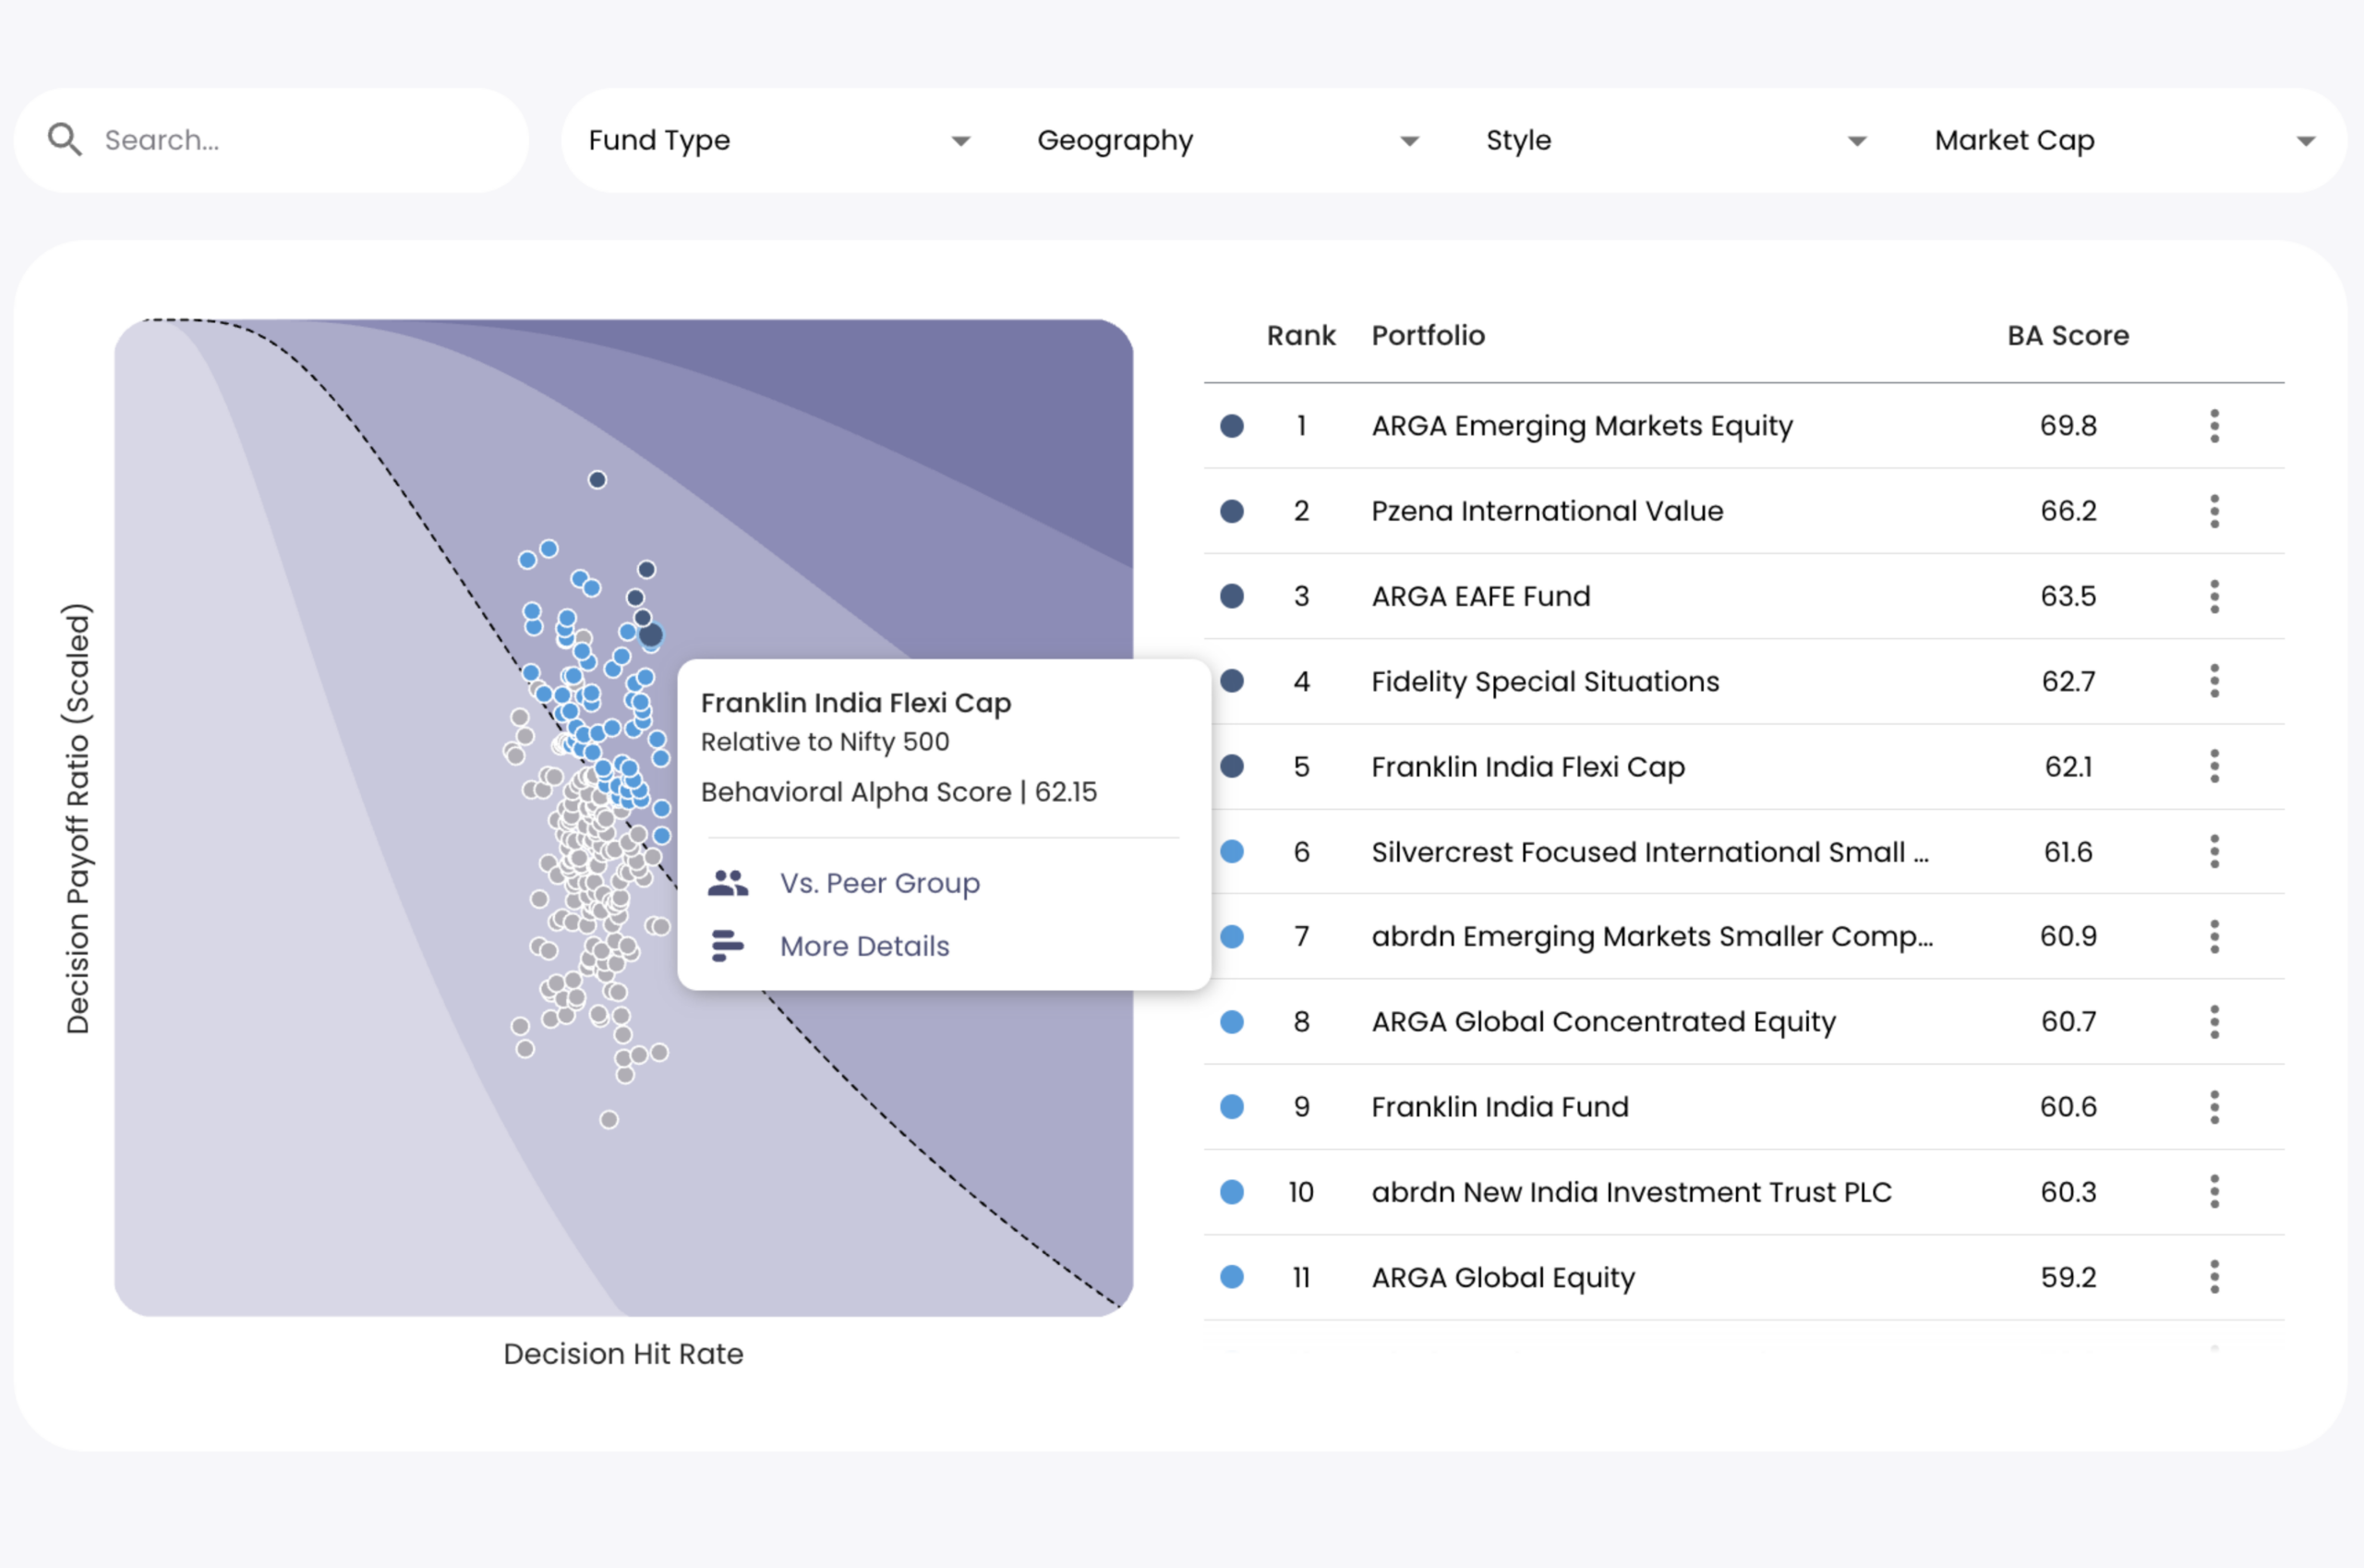
ARGA Emerging Markets Equity retained the No. 1 position with a Behavioral Alpha Score of 69.8, while ARGA EAFE Fund moved from No. 5 to No. 3, giving ARGA two of the Top 3 positions. Pzena International Value Fund advanced four places to No. 2, and Fidelity Special Situations Fund entered the Top 5 for the first time at No. 4.
Across the broader field, decision-making outcomes weakened following the previous quarter’s rebound. The median Behavioral Alpha Score fell to 47.4 from 49.0, and the percentage of portfolios adding value through their overall decision-making declined to 32.7% from 41.7%.
About the Behavioral Alpha® Benchmark
The Essentia Behavioral Alpha Benchmark (EBAB) uses decision attribution analytics to assess portfolio manager skill over a rolling 36-month period. Unlike traditional rankings based on past returns, EBAB evaluates the value added or destroyed through managers’ investment decisions, helping distinguish skill from luck.
The methodology assesses seven key decision types. Each manager’s Behavioral Alpha Score (BA Score) is calculated using their decision hit rate (the percentage of decisions that add value) and payoff ratio (the magnitude of value added by good decisions relative to the value destroyed by bad ones).
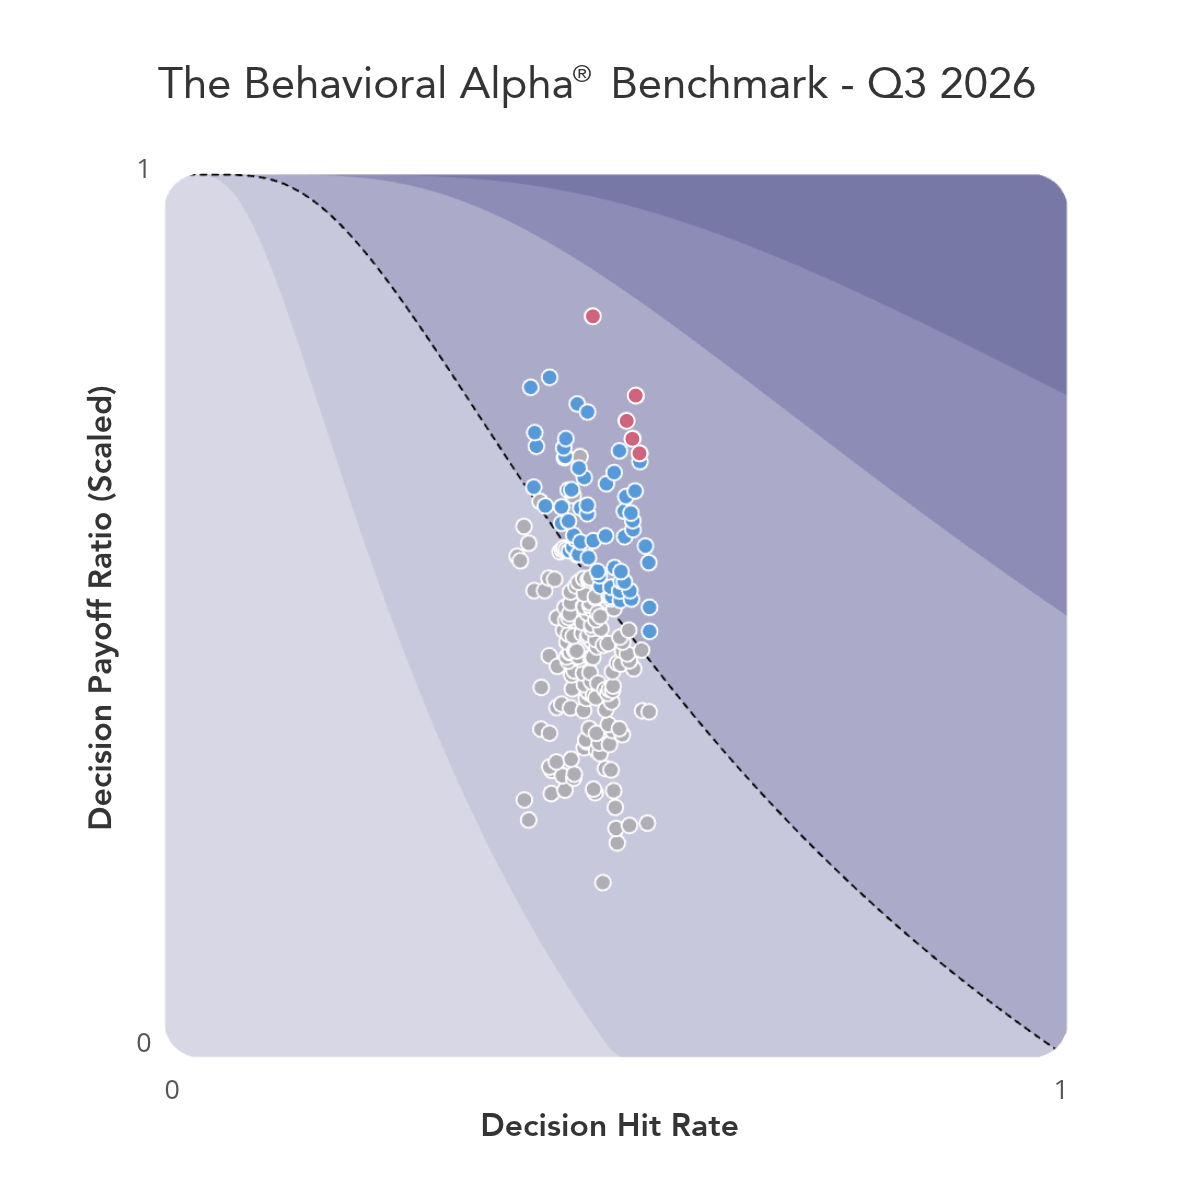
The five highest-scoring managers, represented by the magenta dots, are those towards the upper-right on this frontier diagram — furthest away from 0,0.
A Behavioral Alpha Score above 50 indicates value-additive decision-making. Essentia’s published research has also established a relationship between demonstrated decision-making skill and subsequent relative portfolio returns.
Top 5 Managers for the Three Years to Sept. 30, 2026
The latest assessment evaluated the demonstrated decision-making skill of 205 active equity portfolios. The Top 5 managers are as follows:
| Rank | Manager(s) | Portfolio |
| 1 | ARGA Team Managed | ARGA Emerging Markets Equity |
| 2 | Rakesh Bordia, Caroline Cai, Allison Fisch and John Goetz | Pzena International Value Fund |
| 3 | ARGA Team Managed | ARGA EAFE Fund |
| 4 | Alex Wright and Jonathan Winton | Fidelity Special Situations Fund |
| 5 | Janakiraman Rengaraju, Rajasa Kakulavarapu and Sandeep Manam | Franklin India Flexi Cap Fund |
Key Takeaways and Notable Trends
- ARGA retains the lead with two funds in the Top 3. ARGA Emerging Markets Equity holds the No. 1 position for the second consecutive quarter, while ARGA EAFE Fund advances two places to No. 3. Pzena International Value Fund returns to the Top 5 at No. 2, up from No. 6.
- Fidelity International makes its first Top 5 appearance. Fidelity Special Situations Fund rises 16 places to No. 4, marking Fidelity International’s first appearance among the five highest-ranked portfolios in the Benchmark assessment.
- The ranking universe continues to grow. A record 205 funds and investment trusts qualified for the latest assessment, up from 199 in Q2.
- Overall decision-making scores decline, with weaker stock-picking and sizing results. The median BA Score fell from 49.0 to 47.4, while the percentage of portfolios adding value declined by nine percentage points to 32.7%. Overall hit rates remained broadly unchanged, but payoff ratios weakened. The percentage adding value through stock picking fell from 44.2% to 37.1%, while the percentage adding value through sizing declined from 77.4% to 71.7%.
More data and results are available through Essentia’s Behavioral Alpha Benchmark app. Insight Pro users can drill down on individual decision categories to see where each portfolio has added or destroyed value.
How the BA Score is Calculated
The Behavioral Alpha Score (BA Score) is determined using a systematic approach that evaluates investment decision-making skill over a 36-month period. The methodology isolates skill from market conditions by analyzing managers’ hit rates (the percentage of value-added decisions) and payoff ratios (the relative impact of good versus bad decisions).
Each manager’s score is benchmark-adjusted and calculated based on seven key decision types:
- Stock selection – Did the manager choose stocks that outperformed the benchmark over the last 3 years?
- Entry timing – Did the manager add value through the precise timing of their entry?
- Sizing – Did the manager add value through capital allocation decisions, compared to running an equally-weighted portfolio?
- Scaling in – Did the manager add value through the way they scaled into their positions, or would a basic algorithm have done just as well?
- Size adjusting – Did the manager make beneficial mid-position adjustments?
- Scaling out – Did the manager add value through the way they scaled out of their positions, or would a basic algorithm have done just as well?
- Exit timing – Did the manager add value through the precise timing of their exits?
Aggregate trends from our prior rankings (all based on 36-month timeframes):
| Median BA Score | Percent of portfolios adding value |
Percent of portfolios with a hit rate over 50% |
Percent of portfolios with a payoff over 100% |
|
| Ending 2026-Q3 | 47.4 | 32.7% | 18.5% | 47.8% |
| Ending 2026-Q2 | 49.0 | 41.7% | 18.1% | 54.3% |
| Ending 2026-Q1 | 48.1 | 37.0% | 18.8% | 50.0% |
| Ending 2025-Q4 | 47.7 | 39.3% | 19.0% | 50.3% |
| Ending 2025-Q3 | 49.3 | 48.1% | 21.8% | 56.4% |
| Ending 2025-Q2 | 50.6 | 53.4% | 21.4% | 67.9% |
| Ending 2025-Q1 | 47.8 | 40.2% | 22.1% | 51.6% |
| Ending 2024-Q4 | 48.7 | 43.0% | 31.7% | 55.7% |
| Ending 2024-Q3 | 49.3 | 48.3% | 22.5% | 57.3% |
| Ending 2024-Q2 | 50.3 | 55.7% | 21.6% | 63.6% |
| Ending 2024-Q1 | 51.4 | 56.9% | 25.0% | 65.3% |
| Ending 2023-Q4 | 50.3 | 52.5% | 30.8% | 62.5% |
| Ending 2023-Q3 | 50.6 | 53.3% | 24.4% | 67.8% |
| Ending 2023-Q2 | 50.9 | 56.5% | 28.2% | 71.8% |
| Ending 2023-Q1 | 51.6 | 63.6% | 28.4% | 79.5% |
| Ending 2022-Q4 | NA | 46.7% | 23.3% | 63.3% |
About Essentia Analytics
Essentia Analytics is the leading provider of behavioral data analytics services to professional investors and allocators of capital. Led by a team of experts in investment management, technology and behavioral science, Essentia combines next-generation decision attribution analytics technology with human coaching to help both equity fund managers and allocators identify investment skill and bias — and capture performance that was previously being lost to decision-making deficiencies.
To participate in the Benchmark ranking/awards or use the methodology for manager assessment, click here to get started with the Behavioral Alpha Benchmark app.
To contact us, please complete the form below.
